CaliClaims Law
one call. that's all
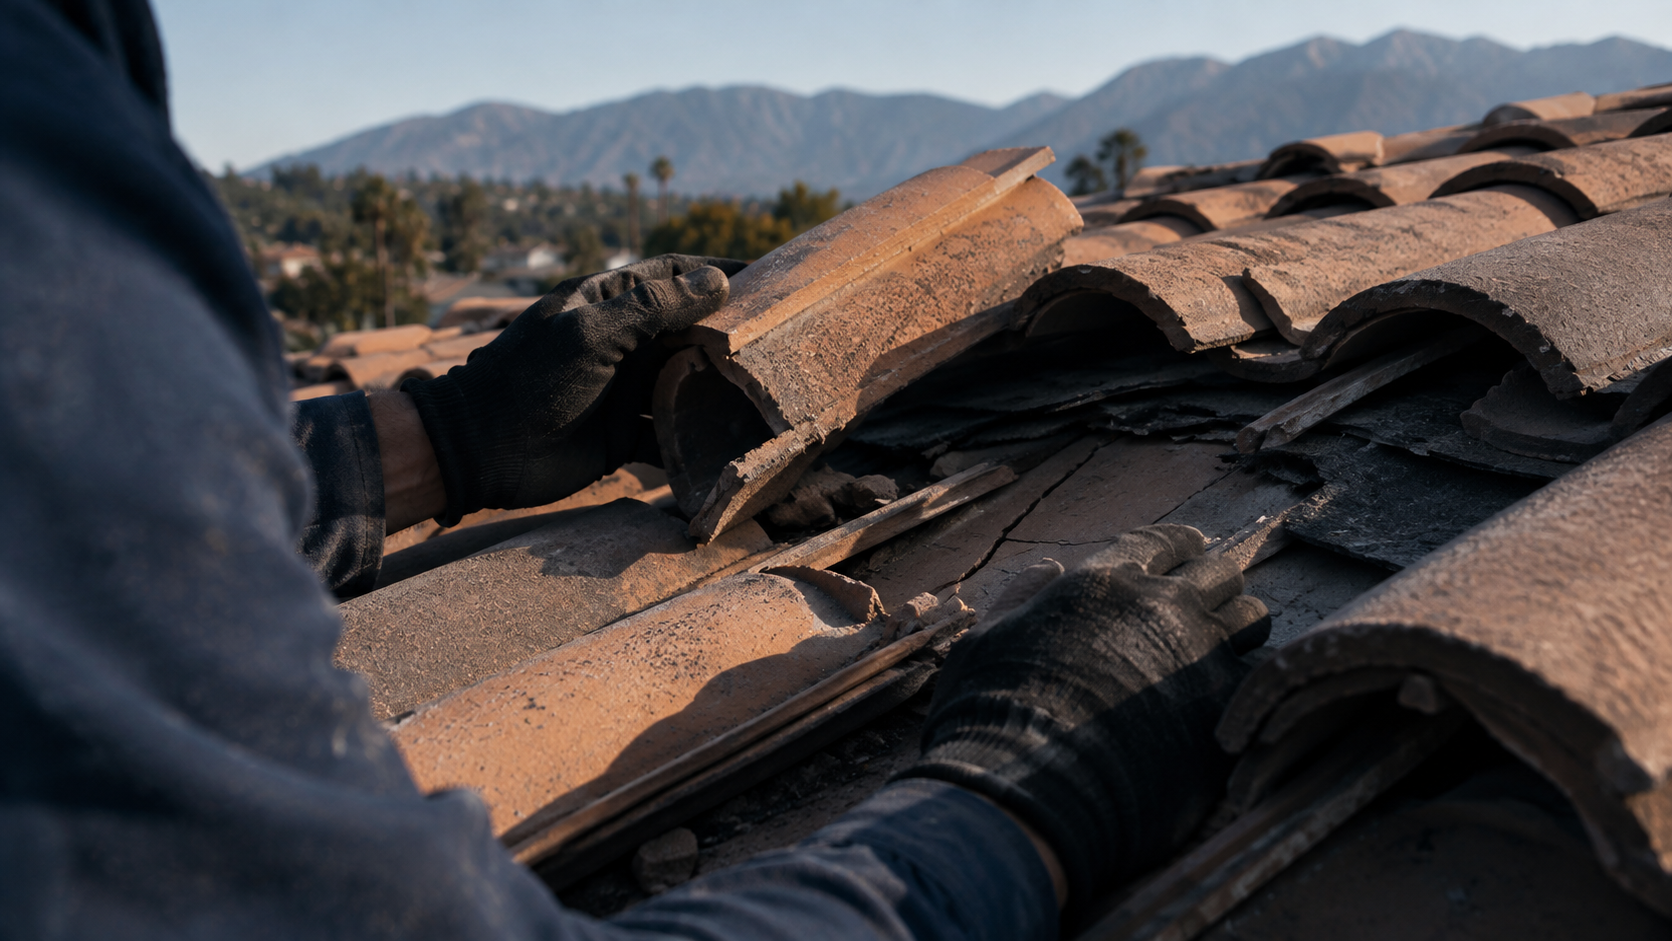
Roof claims are among the most frequently disputed property claims in California, and the reason is structural to how roofs age. Every roof deteriorates. Every storm that damages a roof damages one that was already aging. That overlap gives carriers a durable argument, and it is the argument most roof claim denials rest on.
None of that makes a roof claim unwinnable. It means the claim turns on evidence connecting a specific event to specific damage, and that evidence is easiest to gather in the days right after the loss rather than months into a dispute.
This guide covers what a typical homeowner policy pays for on a roof, why wear and tear is the central battleground, how actual cash value and replacement cost coverage produce very different settlements, and what to document from the start.
Most standard homeowner policies cover sudden and accidental roof damage caused by a covered peril. In Southern California the ones that come up most are wind, fire, falling objects such as tree limbs, and water intrusion following one of those events. Hail appears in some policies and is excluded or limited in others.
What policies generally do not cover is deterioration. Wear and tear, gradual aging of roofing material, damage attributable to deferred maintenance, and manufacturing defects are typically excluded. Some policies also limit damage to roofs above a certain age, or settle older roofs on a depreciated basis regardless of how the rest of the dwelling is covered.
These exclusions are ordinary and generally enforceable. The dispute is almost never about whether wear and tear is excluded. It is about whether the damage in front of the adjuster is wear and tear, or is storm damage to a roof that happened to be older.
The common pattern: a storm passes, a homeowner reports damage, an adjuster or an engineer retained by the carrier inspects, and the report concludes the damage is consistent with age and long term exposure rather than with the reported event. The claim is then denied or reduced to something well below the cost of the work.
What tends to move that conclusion:
The carrier's report is an opinion rather than a determination. Opinions can be answered with other opinions and with evidence the first one did not consider.
Storm and wind claims are commonly reduced by attributing damage to age or maintenance rather than the weather event. That call can determine what gets paid. Send the adjuster's report, the estimate, or the denial letter, and we review your policy alongside the insurer's reasoning. Nothing is owed upfront.
Get my free claim reviewThis single distinction accounts for a large share of the surprise in roof settlements, and many homeowners do not learn which coverage they bought until they read the settlement letter.
Replacement cost coverage pays what it costs to replace the roof at current prices. Actual cash value coverage pays that amount less depreciation for the roof's age and condition, which on an older roof can be a substantial reduction.
Two practical points follow. First, many replacement cost policies pay in two stages: an actual cash value amount up front, with the withheld depreciation released after the work is completed and documented, usually within a deadline stated in the policy. Money left unclaimed at that stage is common and avoidable. Second, some policies contain a roof specific endorsement that settles the roof on an actual cash value basis even where the rest of the dwelling is on replacement cost. Check the declarations page and the endorsements rather than assuming.
Where a policy provides replacement cost but the settlement applies a depreciation schedule that is never released, the coverage purchased has effectively been converted into something narrower. That is worth raising in writing.
A second recurring dispute is scope. A carrier may authorize repair of a damaged section where a roofer's position is that a partial repair is not sound, or that available replacement materials will not reasonably match the existing roof.
Matching questions arise because roofing materials change. Discontinued profiles, color runs that no longer exist, and tile shapes no longer produced all make a partial repair visibly different from the rest of the roof. Whether a policy owes a reasonably uniform appearance depends on the policy language and the circumstances, which makes this a coverage question to put to the carrier directly rather than an argument about preference.
Situations where legal review tends to be worthwhile:
CaliClaims Law reads the policy first, including any roof specific endorsement, then maps the carrier's report against the contractor's assessment to identify exactly where the two disagree and what evidence answers it. Reviews are free and there is no obligation. Call (949) 996-7534.
Age alone does not usually make a claim uncoverable, but it matters in two ways. It supports a carrier's argument that damage is deterioration rather than event related, and some policies contain endorsements that settle older roofs on an actual cash value basis. The declarations page and any roof endorsement will show which applies.
Replacement cost pays what a new roof costs at current prices. Actual cash value pays that amount reduced by depreciation for age and condition. On an older roof the difference can be considerable, which is why identifying the coverage before responding to a settlement offer matters.
Not automatically. Carriers frequently authorize repair of the damaged area only. Whether replacement is owed depends on whether a sound repair is possible and on how the policy treats matching of materials. A licensed contractor's written opinion that a partial repair is not sound is the useful starting point.
No. An engineering report is evidence and an opinion, not a final determination. It can be answered with a competing assessment, weather data for the date of loss, records of the roof's pre-loss condition, and evidence the report did not consider.
Nothing. CaliClaims Law reviews roof and property insurance claims at no charge and works on a contingency basis, meaning no upfront fees and no hourly billing. Call (949) 996-7534.