CaliClaims Law
one call. that's all
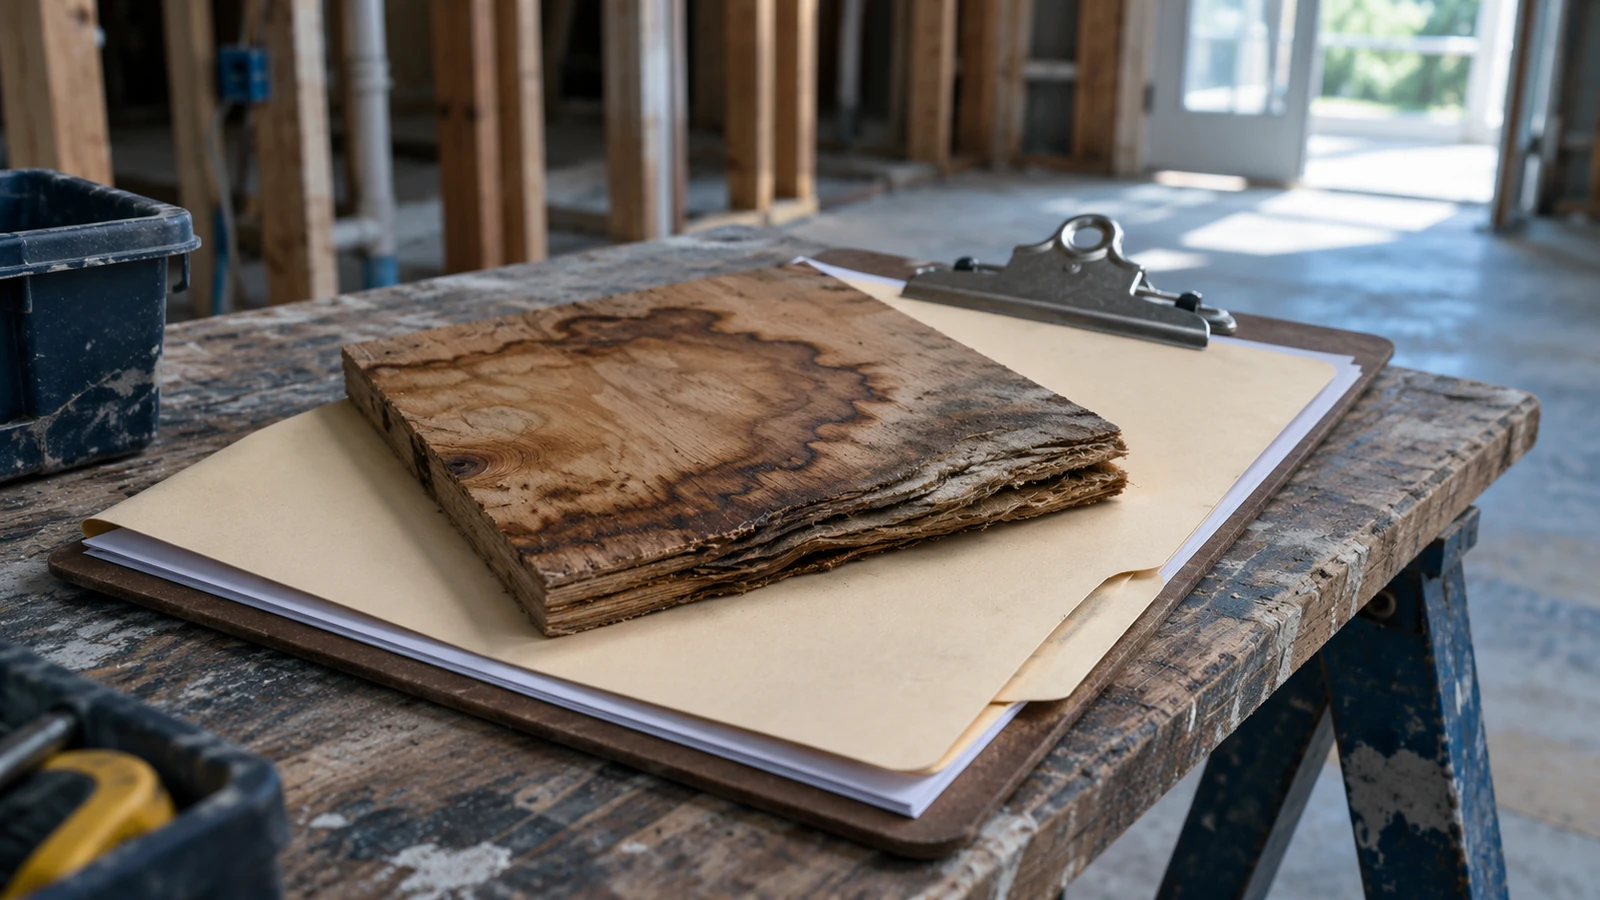
The first check rarely ends a property claim. Repairs begin, a wall comes down, and the contractor finds charred framing behind clean drywall or a subfloor soaked well past where the adjuster's estimate stopped. Plan check comes back with code corrections nobody priced. The estimate turns out to have skipped a room. Each of those produces a supplemental claim, and each is normal.
Carriers know supplements are normal, which is why their handling of them is such a reliable measure of a file. Some pay documented supplements on receipt. Others treat the first payment as the finish line and every request after it as an attempt to reopen something settled. The policy does not support the second view, but a policyholder who does not know that will often accept it.
This article covers what a supplemental claim is, when one is available, how a release changes the analysis, and how to document a supplement so that it gets paid rather than argued. Coverage always depends on the specific policy language and the facts of the loss.
A supplement is a request for additional payment on an existing claim. It carries the same claim number, the same date of loss, and the same deductible, which has already been applied. It does not count as a second claim on the policyholder's claims history, and it does not require the carrier to reopen anything in the legal sense, because nothing was closed except a file folder.
The usual kinds fall into a short list. Hidden damage exposed during repairs is the largest category: heat damage behind drywall, wet framing under flooring, smoke in ductwork, a cracked slab beneath a finished floor. Code-required work identified at plan check is the second, and it belongs under the ordinance or law coverage discussed elsewhere on this site. Items the first estimate missed or priced below market are the third, and they are found by comparing the contractor's scope to the adjuster's line by line. Contents discovered later, living expenses that ran longer than projected, and the replacement cost holdback released after repairs are all handled through the same channel.
What a supplement is not also matters. Damage from a separate later event, such as a second storm, is a new claim with its own deductible. Deterioration the contractor happened to expose that has no connection to the loss is not part of the claim at all, though the cost the covered repair has to absorb to work around it can be, and that distinction gets argued on nearly every large file.
The policy does not limit how many supplements a claim can carry. The carrier's obligation is to pay what the policy owes for the loss, and that obligation continues until the loss has been fully paid. A carrier that closes a file after issuing a payment has made an administrative choice, reversible by a letter, and the policyholder who hears that the claim is closed should ask, in writing, what provision of the policy the carrier believes closed it.
The outer boundary is time. The policy's own suit clause and California's statutory framework set how long a policyholder has to pursue an unpaid claim, and the numbers are deliberately left out of this article because they turn on the policy and the facts. What can be said generally is that California law pauses the policy's suit clock while the carrier is handling the claim and restarts it only when the carrier denies the claim in writing, and that state law sets minimum periods for collecting replacement cost after repairs, longer for losses tied to declared emergencies. A supplement submitted while the claim is being handled is inside the window.
A release changes everything above. If the policyholder signed a document that releases the carrier from further liability for the loss, or for specific items, the supplement for those items may be barred. Routine property payments do not usually come with releases, but disputed settlements sometimes do, and an appraisal award fixes the amount of loss for the items that were appraised. A release signed under pressure, or on a shared mistaken belief about how much damage existed, raises questions worth putting to counsel rather than assuming the answer either way.
The practical trigger is discovery. The moment new damage is found, the work in that area stops, photographs are taken, the carrier is notified in writing, and a re-inspection is requested before anything is covered up. Failing to give the carrier a chance to see the damage is the single most common reason a legitimate supplement gets denied, and it is entirely avoidable.
Lack of notice leads the list. A supplement for framing that has already been replaced and drywalled over asks the carrier to pay for something it never saw, and most will refuse. Photographs taken at discovery, with a date and the contractor's notes, solve most of that problem; a re-inspection solves the rest.
Attribution comes next. The carrier accepts that the damage exists but argues it predates the loss or came from something excluded, such as long-term seepage or insect damage that the repair exposed. Sometimes that is right. The answer is a contractor's written explanation connecting the newly found damage to the loss, and, where the connection is arguable, the mixed-cause analysis California applies when covered and excluded causes combine.
Pricing and format make up the middle of the list. The carrier wants the supplement in the format of its own estimate, with unit costs it can compare, and objects to a contractor's lump-sum change order. Producing a line-item supplement that mirrors the carrier's structure is tedious and worth it, because it turns the argument into arithmetic. Claims that an item was already paid are answered the same way, by pointing to the line, or the missing line, in the original estimate.
Depreciation and timing finish the list. Carriers sometimes apply fresh depreciation to supplement items or hold the entire replacement cost holdback until every last repair is done, and both practices deserve a written challenge. Timeliness objections, the assertion that the claim is closed or too old, get answered with the policy language and the clocks described above.
When new damage appears, work in that area pauses until it is photographed with a date and a reference to its location. The contractor's foreman is usually the one holding the phone, and a two-minute habit protects the whole supplement.
Send the carrier the photographs and a short description the same day, and ask for a re-inspection before the area is repaired. If the carrier declines to inspect, that decision is in writing and the repair can proceed.
Each supplement line gets a quantity, a unit cost, and one sentence on why it was not in the original scope: concealed, discovered at demolition, required by plan check, or omitted from the estimate. Reasons preempt the attribution argument.
Have the contractor build the supplement in the same line-item structure the carrier used, so each item can be compared or shown to be missing. Format is not a concession; it is what makes the supplement easy to pay.
Track the original estimate, every payment, every supplement, and the depreciation holdback in a single running document. Carriers lose track of their own payments, and the policyholder with the ledger is the one who gets believed.
Do not sign a document with release language to obtain a payment without understanding what it releases. Most payment paperwork is not a release. The document that is one will say so, and it deserves a careful read before the check is cashed.
Whatever the claim type, the first step is the same. Send the denial letter, the estimate, or just the story. We read your policy, the insurer's position, and the gap between them, then tell you where you stand. There are no upfront fees, and fees come only out of a recovery.
Get my free claim reviewCalifornia's fair claims settlement regulations do not distinguish between a first submission and a supplement. Communications about the claim must be acknowledged and answered within the regulatory clocks, a decision to pay less than the amount claimed must be explained in writing with the policy provisions and facts relied on, and the investigation behind that decision must be thorough. A supplement that sits unanswered for months is a regulatory problem for the carrier regardless of what the file's status field says.
The suit clause in California property policies is read in the policyholder's favor on timing. The clock is paused from the time the claim is reported until the carrier denies it in writing, so a claim that has never been formally denied has not been running out the clock while supplements are exchanged. Replacement cost holdbacks have their own statutory minimum periods, extended after declared emergencies and for good cause when repairs are delayed for reasons outside the policyholder's control. None of those periods are stated here because they should be confirmed for the specific claim rather than applied from memory.
Releases are governed by contract law, which means the document means what it says and no more. A release limited to specific items leaves the rest of the claim open. A general release of all claims arising from the loss is a different document, and one that carriers rarely obtain on a routine property payment. Where a release was signed on the basis of a shared mistaken belief about the extent of the damage, or under pressure that the law recognizes, there may be grounds to challenge it, and those are questions for counsel with the document in hand.
The firm audits the original estimate and the payment history before touching the supplement, because half of what looks like a supplement turns out to be an item the first estimate should have carried. The remainder is documented at discovery, submitted with a re-inspection request, and built in the carrier's own format with a reason on every line.
Attribution disputes get a contractor's written analysis and, where causes are mixed, the California rule that governs them. Clocks are tracked, holdbacks are demanded on schedule, and any document with release language is read before anyone signs it. The work is done for the policyholder alone.
Past results do not guarantee a similar outcome. Every claim is different.
In most cases, yes. Closing a file is an administrative step, not a policy provision. Unless you signed a release, the claim stays open under the policy and California's timing rules, and a written supplement with photographs and an itemized estimate obligates the carrier to respond. Ask the carrier to identify the provision it believes closed the claim.
No. A supplement is part of the original claim, with the same date of loss and the deductible that was already applied. A carrier that deducts again on a supplement has made an error, and it should be corrected in writing.
The termite damage itself is excluded on a standard policy. The costs the covered fire repair has to absorb to work around it, such as additional demolition or code-driven replacement, are analyzed separately and are often part of the claim. The contractor's written breakdown of which is which is what makes that argument.
Probably not. Most payment paperwork is a proof of loss, a payment acknowledgment, or a mortgage endorsement form, none of which release the claim. A true release says so in its terms. Send the document for a read before assuming either answer.
Send the original estimate, the payment history, your contractor's supplement, and the photographs from discovery. The firm compares the scopes line by line, checks the clocks and any release language, and tells you what the carrier still owes. CaliClaims Law reviews property insurance claims for Southern California policyholders at no cost. One call. That's all.