CaliClaims Law
one call. that's all
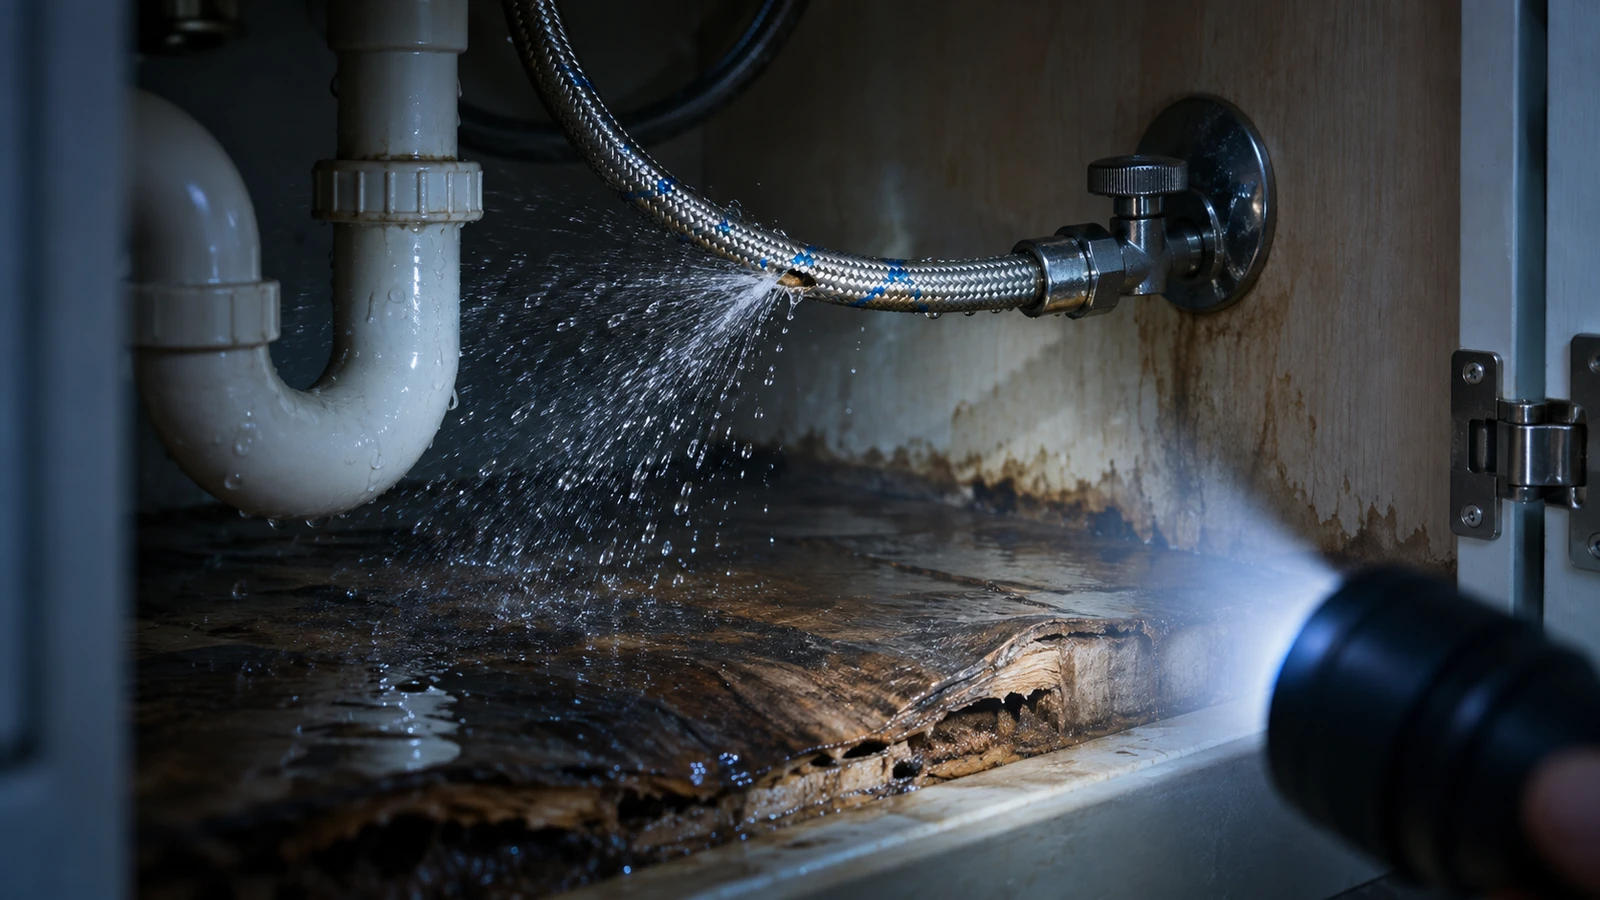
The supply line under your upstairs vanity splits on a Tuesday afternoon, and by evening water has come through the kitchen ceiling below. When the contractor opens the floor, the plywood around the toilet flange is dark and soft from a slow seep that predates the break. The denial letter cites the exclusions for deterioration and continuous seepage and applies them to the whole loss. The carrier has picked the cause that frames its decision. California has a rule for testing that pick.
If you're holding a letter like that, one that concedes something covered happened and then points to something excluded, California calls the situation concurrent causation, whether or not the letter uses the term. The same pattern appears when a windstorm tears open flashing that was installed poorly years ago, or when a broken drain saturates the soil under a foundation.
The California rule is called the efficient proximate cause doctrine. It starts with two short sections of the Insurance Code, was shaped by two California Supreme Court decisions, and has been tested by policy wording written to get around it. Coverage always depends on the specific policy language and the facts of the loss.
Concurrent causation describes a loss that more than one cause helped produce. The hard cases are the ones where at least one cause is generally covered (windstorm, a sudden discharge of water, a third party's negligence) and at least one is excluded (deterioration, continuous seepage, faulty workmanship, earth movement).
Sometimes the causes form a chain: wind lifts flashing, the opening lets in rain, the rain soaks the drywall. Sometimes an excluded condition sets the stage and a covered event does the damage, as when a corroded line bursts. Either way, the common carrier argument is that the excluded condition was part of the picture.
California does not accept "part of the picture" as the test. For first-party property claims, meaning claims on your own homeowners or commercial property policy, California courts look for the cause that predominated. If that cause is covered, the loss is generally covered even though an excluded cause contributed, and the reverse generally holds too. Most of these disputes come down to which cause predominated, a question of fact built from evidence about your particular property.
The starting point is Insurance Code §530. It provides that an insurer is liable for a loss of which a peril insured against was the proximate cause, even though a peril the contract did not contemplate may have been a remote cause, and that the insurer is not liable for a loss of which the insured peril was only a remote cause.
Insurance Code §532 pulls the other way. It provides that if a peril is specially excepted in the policy and there is a loss that would not have occurred but for that peril, the loss is excepted even though the immediate cause was a peril that was not excepted. Read alone, §532 sounds like a "but for" test.
Almost every loss in an older building has some excluded condition without which the damage might not have happened, so a literal §532 would let one excluded cause anywhere in the chain defeat the whole claim. The California Supreme Court resolved that conflict in 1963.
In Sabella v. Wisler (1963) 59 Cal.2d 21, a house had been built on poorly compacted fill. A sewer line near the foundation broke and leaked, the water saturated the unstable soil, and the house settled and cracked. The policy excluded settling and cracking of foundations and walls. The insurer argued §532's "but for" language excluded the loss.
The court held that §532 must be read together with §530, so its "but for" peril means the peril that proximately caused the loss, and its "immediate cause" means the cause closest in time to the damage. It adopted the rule that when different causes concur, the efficient cause, the one that sets others in motion, is the cause to which the loss is attributed. The court treated the ruptured sewer line, which it attributed to a third party's negligence, as the efficient cause, held that the settling exclusion did not bar recovery on that basis, and ordered a new trial on the insurer's liability. For a denial letter, an excluded condition downstream of a covered event does not by itself decide the claim.
Twenty-six years later, Garvey v. State Farm Fire & Casualty Co. (1989) 48 Cal.3d 395 confirmed that this is the rule for first-party property claims. A room addition had pulled away from the main house; negligent construction was not excluded, while earth movement and foundation settling were. The Supreme Court held that a concurrent-cause approach drawn from a liability insurance case belongs only in liability cases and that Sabella governs property losses. It described the efficient proximate cause as the predominating cause, held that the question of causation is for the jury to decide, and affirmed the Court of Appeal with directions to remand for further proceedings. A mixed-cause property claim is measured by predominance.
California's civil jury instruction on this point, CACI No. 2306, tells jurors that when a loss is caused by a combination of covered and excluded risks, the loss is covered only if the most important or predominant cause is a covered risk. Its directions for use explain that under an all-risk policy, once the insured establishes basic coverage, the insurer bears the burden of proving the loss was caused by an excluded peril; under a named-perils policy, the insured carries the burden of proving the specified peril. The cause a denial letter names, in other words, has to be the predominant one, not simply a cause that was present.
Policy forms often open an exclusion section with a lead-in stating that the listed perils are excluded no matter what other cause or event contributed, whether at the same time or in any order. This is the anti-concurrent causation clause. It tries to make any involvement of an excluded peril enough, which is close to the literal reading of §532 that Sabella rejected.
California courts have limited how far that language reaches. In Howell v. State Farm Fire & Casualty Co. (1990) 218 Cal.App.3d 1446, a fire stripped a slope, heavy rains followed, and a landslide damaged the property. The policies excluded earth movement, and one of them used "concurrently or in any sequence" lead-in wording. The Court of Appeal held that the exclusions were not enforceable to the extent they purported to limit the insurer's liability beyond what §530 permits, and it reversed summary judgment for the insurer so that a jury could decide whether the fire was the efficient proximate cause.
The California Supreme Court took up a related clause in Julian v. Hartford Underwriters Ins. Co. (2005) 35 Cal.4th 747, a Los Angeles County case in which heavy rain triggered a landslide above a home. The policy excluded weather conditions when they contribute in any way with an excluded cause such as earth movement. The court restated that policy exclusions are unenforceable to the extent they conflict with §530 and the efficient proximate cause doctrine. It also held that insurers may cover some manifestations of a peril and exclude others, and that "rain inducing a landslide" is a genuine, commonly understood peril, so the weather clause as applied to that loss did not violate §530. The court limited its holding to that application.
The Court of Appeal applied the same principles to a coverage grant in Vardanyan v. AMCO Ins. Co. (2015) 243 Cal.App.4th 779, a water-damage and collapse claim. The policy covered collapse "caused only by" listed perils, and the insurer read that phrase to defeat coverage whenever any unlisted peril contributed. The court held that, to the extent the phrase is read that way, it is "an unenforceable attempt to contract around the efficient proximate cause doctrine," and it held that CACI No. 2306 was the correct instruction to give the jury.
Read together, these decisions mean the opening words of an exclusion, or the restrictive words of a coverage grant, are not self-executing in California. Sweeping language can be limited where it conflicts with §530, while a defined, commonly understood peril may be excluded as written.
Storm and wind claims are commonly reduced by attributing damage to age or maintenance rather than the weather event. That call can determine what gets paid. Send the adjuster's report, the estimate, or the denial letter, and we review your policy alongside the insurer's reasoning. Nothing is owed upfront.
Get my free claim reviewTwo patterns come up often in Southern California files, and two habits help with both.
Go back to the split vanity line. The ceiling below, the kitchen cabinets, and the drywall it soaked in a single afternoon have one history. The soft plywood around the toilet flange has another. A single claim file can hold both a loss whose predominant cause is a sudden discharge and a loss whose predominant cause is years of seepage, and the causation question can be asked of each area separately. A letter that applies the seepage exclusion to the entire loss treats the two histories as one. The same separation question arises with corroded cast-iron drain lines, where internal corrosion sits behind a sudden failure.
A windstorm peels back a run of chimney flashing on a tile roof that is otherwise sound, and the next rain reaches the attic. Windstorm is generally a covered peril, and many policy forms cover interior rain damage only when wind or hail first creates an opening. The carrier's inspector then notes that the flashing was under-fastened when it was installed, and the letter cites the faulty workmanship exclusion. Two questions follow. First, a sequence question: did the storm create the opening before the rain arrived, which is the condition the rain coverage turns on? Second, a predominance question: was the wind the force that set the loss in motion, or was the installation so deficient that ordinary weather would have produced the same opening? Storm damage claims in Southern California and the question of whether homeowners insurance covers a roof leak both meet this workmanship issue sooner or later.
Read the exact lead-in to each exclusion the letter cites, and note whether it says the exclusion applies regardless of other causes, concurrently or in any sequence, or when the peril contributes in any way. That is the language Howell and Julian examined. Then read the coverage grant for the part of the property involved and note any restrictive phrasing, such as "caused only by," which is the Vardanyan issue. Note whether the exclusion names a defined peril or reaches for any contribution at all, and whether the policy restores coverage for ensuing loss, meaning damage from a covered peril that follows an excluded one.
Predominance is a question about sequence and weight, so the record that matters is the one that shows order. Write down, with dates, what failed first and what followed: the moment of the break or the storm, when water was first seen and where, and when each area was opened up. Mark each area of damage on a floor plan or on the estimate and note which cause the evidence ties it to. Gather dated records of the property's condition before the event, aimed at the "would have happened anyway" argument. Ask the carrier in writing which cause it says predominated for each area. California's fair claims regulations, which govern the California property insurance claim process, require insurers to explain the basis for a denial, and that stated basis is what the causation record gets measured against.
When a denial rests on an excluded cause, the firm starts by separating every cause the carrier names and asking which one set the loss in motion. Its work is limited to property insurance claims, and it acts for policyholders, never for insurers.
On a causation denial, the review starts with the letter, the full policy including each cited exclusion's lead-in and the relevant coverage grant, and the evidence of what happened to the property. The firm compares the cause the carrier names against the record on predominance and what California law allows the wording to do. The claim review is free, and the firm is only paid if there is a recovery in the case.
Past results do not guarantee a similar outcome. Every claim is different.
It is the situation where two or more causes combine to produce one loss, typically one the policy generally covers and one it excludes. California property claims resolve it under the efficient proximate cause doctrine, which looks to the predominant cause rather than to whether an excluded cause was involved at all.
Not to the extent they conflict with Insurance Code §530 and the efficient proximate cause doctrine, according to the California Supreme Court in Julian. Courts have declined to apply sweeping "any contributing cause" language that way, while the same court upheld a weather exclusion as applied to a rain-induced landslide. How a given clause applies depends on its wording and the facts of the loss.
In litigation, Garvey treats it as a question for the jury. Before any lawsuit, the carrier makes its own determination in the claim decision, and the evidence in the file (the timeline, trade findings, weather data, inspection reports) is what that determination is tested against.
Yes. Different areas of damage in the same loss can have different predominant causes, so a claim may generally be covered for some areas and excluded for others. How the line is drawn depends on the policy language and on evidence tying each area of damage to its cause.
Yes. The review looks at the denial letter, the policy wording the carrier relies on, and the evidence of how the damage happened, and gives you a direct read on where the causation question stands. CaliClaims Law reviews property insurance claims for Southern California policyholders at no cost. One call. That's all.